
Money One-page note UK only
How Workplace Pensions Work
Your workplace pension usually gets free money from your employer, plus a top-up from the government. Here's how it works. UK only. Save this page.
Good to know
UK rules 2026/27. General info, not financial advice.
What's on the page
The note as text, so you can read it, copy it or use a screen reader.
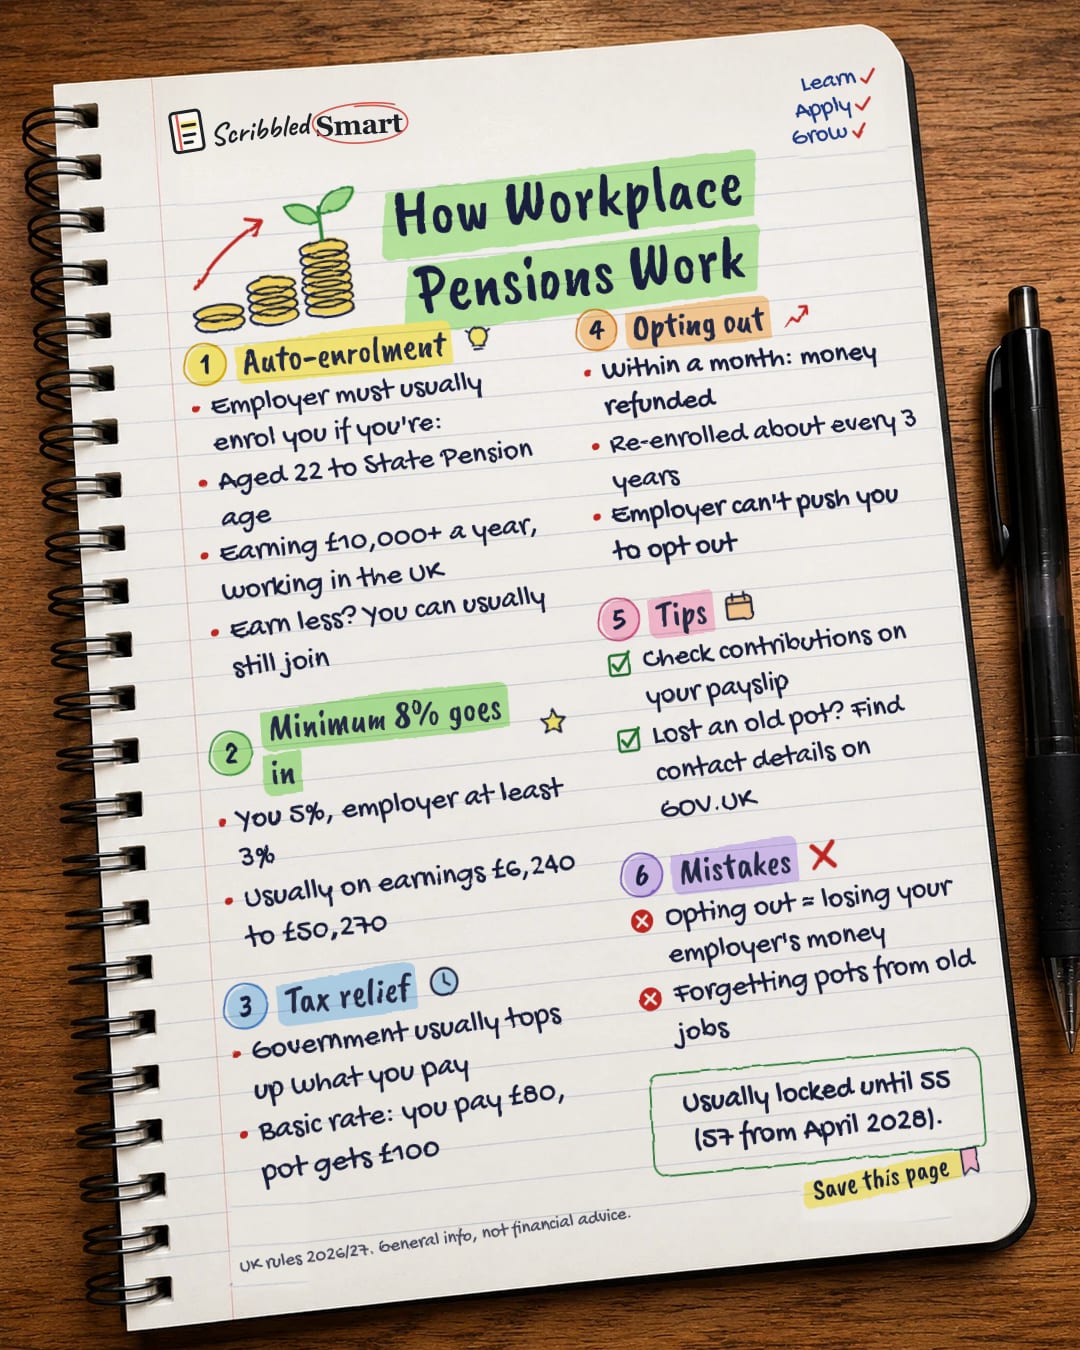
Auto-enrolment
- Employer must usually enrol you if you're:
- Aged 22 to State Pension age
- Earning £10,000+ a year, working in the UK
- Earn less? You can usually still join
Minimum 8% goes in
- You 5%, employer at least 3%
- Usually on earnings £6,240 to £50,270
Tax relief
- Government usually tops up what you pay
- Basic rate: you pay £80, pot gets £100
Opting out
- Within a month: money refunded
- Re-enrolled about every 3 years
- Employer can't push you to opt out
Tips
- Check contributions on your payslip
- Lost an old pot? Find contact details on GOV.UK
Mistakes
- Opting out = losing your employer's money
- Forgetting pots from old jobs
Sources
- GOV.UK: Joining a workplace pension
- GOV.UK: What you, your employer and the government pay
- GOV.UK: If you want to leave your workplace pension scheme
- The Pensions Regulator: Earnings thresholds
- The Pensions Regulator: Safeguarding individuals
- The Pensions Regulator: Opting out (business advisers)
- GOV.UK: Find pension contact details
- GOV.UK: Increasing Normal Minimum Pension Age
- HM Treasury: Budget 2026
How we checked this
Every fact on this note comes from the 9 sources listed here, checked against official or peer-reviewed sources where possible. AI tools help with drafting; a person checks every fact against the sources. How we research
Spotted a mistake? Tell us and we'll fix it and log it on the corrections page.


