
Money One-page note UK only
Remortgaging: What to Do Before Your Fix Ends
Fixed-rate mortgage ending soon? Do nothing and you could pay about £145 a month more. Here's what to do and when. Save this page.
Good to know
UK. Rates: Bank of England averages, Oct 2026 (75% LTV). Example only. General info, not financial advice.
What's on the page
The note as text, so you can read it, copy it or use a screen reader.
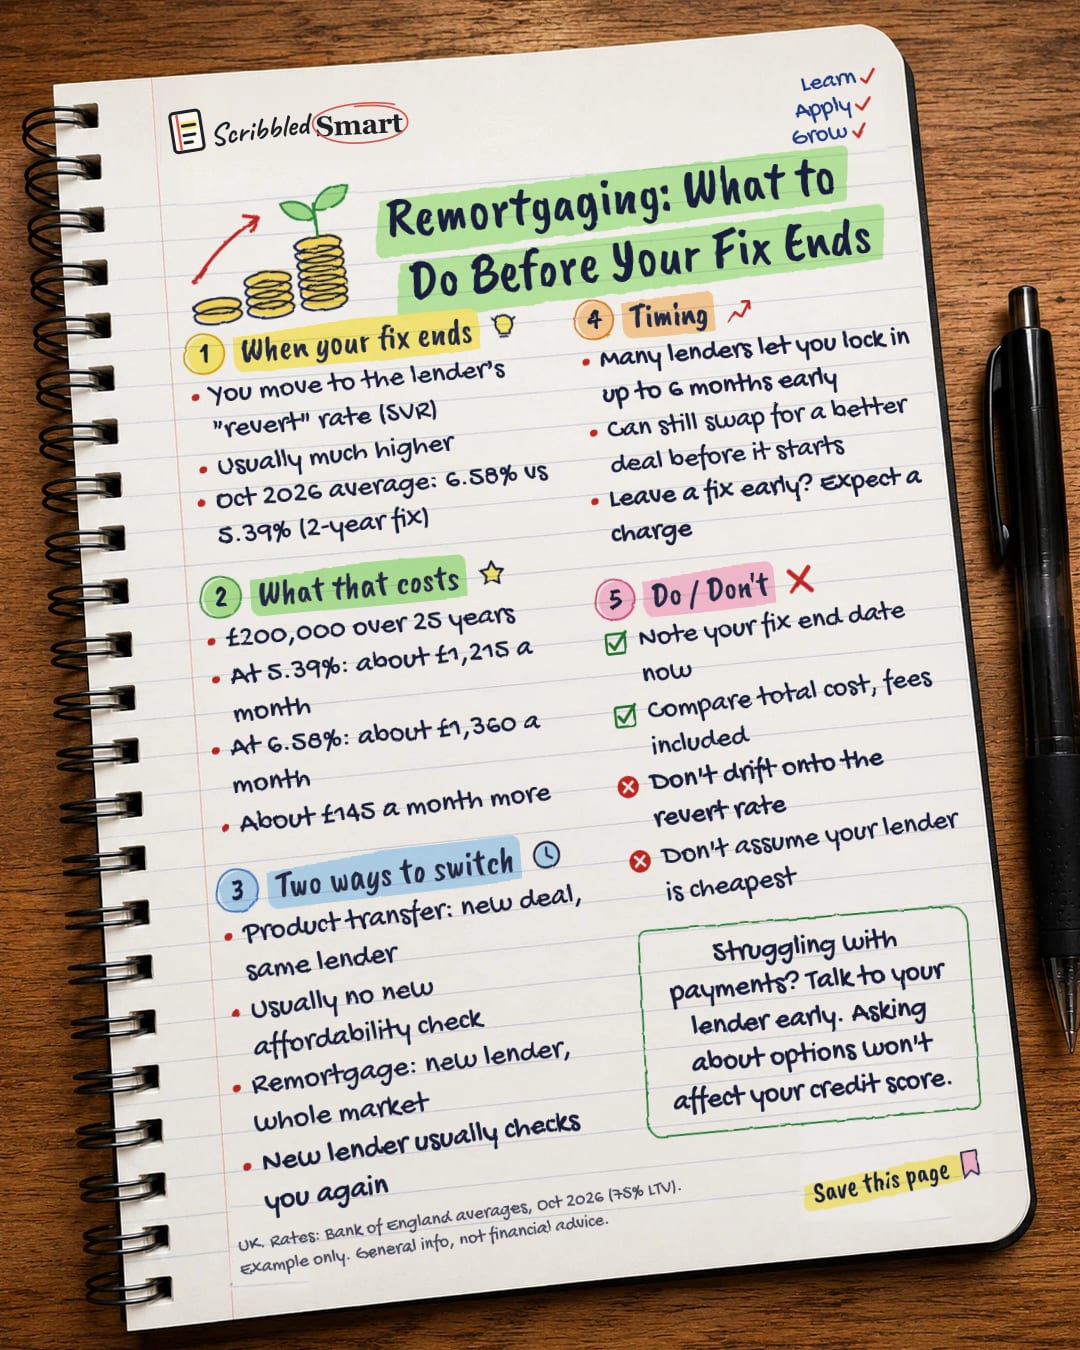
When your fix ends
- You move to the lender's "revert" rate (SVR)
- Usually much higher
- Oct 2026 average: 6.58% vs 5.39% (2-year fix)
What that costs
- £200,000 over 25 years
- At 5.39%: about £1,215 a month
- At 6.58%: about £1,360 a month
- About £145 a month more
Two ways to switch
- Product transfer: new deal, same lender
- Usually no new affordability check
- Remortgage: new lender, whole market
- New lender usually checks you again
Timing
- Many lenders let you lock in up to 6 months early
- Can still swap for a better deal before it starts
- Leave a fix early? Expect a charge
Do / Don't
- Note your fix end date now
- Compare total cost, fees included
- Don't drift onto the revert rate
- Don't assume your lender is cheapest
Sources
- Bank of England: Database, quoted household interest rates (IUMTLMV revert-to-rate; IUMBV34 2-year fixed 75% LTV; IUMBV42 5-year fixed 75% LTV), Oct 2026
- HM Treasury: Mortgage Charter (updated 19 Dec 2025)
- FCA: FCA helps people navigate their financial lives with simplified mortgage rules (22 Jul 2025, updated 5 Dec 2025)
- FCA: PS25/11 Mortgage Rule Review: First steps to simplify our rules and increase flexibility
- Financial Ombudsman Service: Interest rates applied to mortgages
- Which?: Switching your mortgage (search summary)
How we checked this
Every fact on this note comes from the 6 sources listed here, checked against official or peer-reviewed sources where possible. AI tools help with drafting; a person checks every fact against the sources. How we research
Spotted a mistake? Tell us and we'll fix it and log it on the corrections page.


