
Money One-page note UK only
Annuity vs Drawdown
At retirement you can swap your pension pot for an income for life, or keep it invested and draw from it. Here's the trade-off. Save this page.
Good to know
UK. Defined contribution pensions. Tax-free cash limit and £10,000 money purchase annual allowance 2026–27. Checked Nov 2026. General info, not financial advice.
What's on the page
The note as text, so you can read it, copy it or use a screen reader.
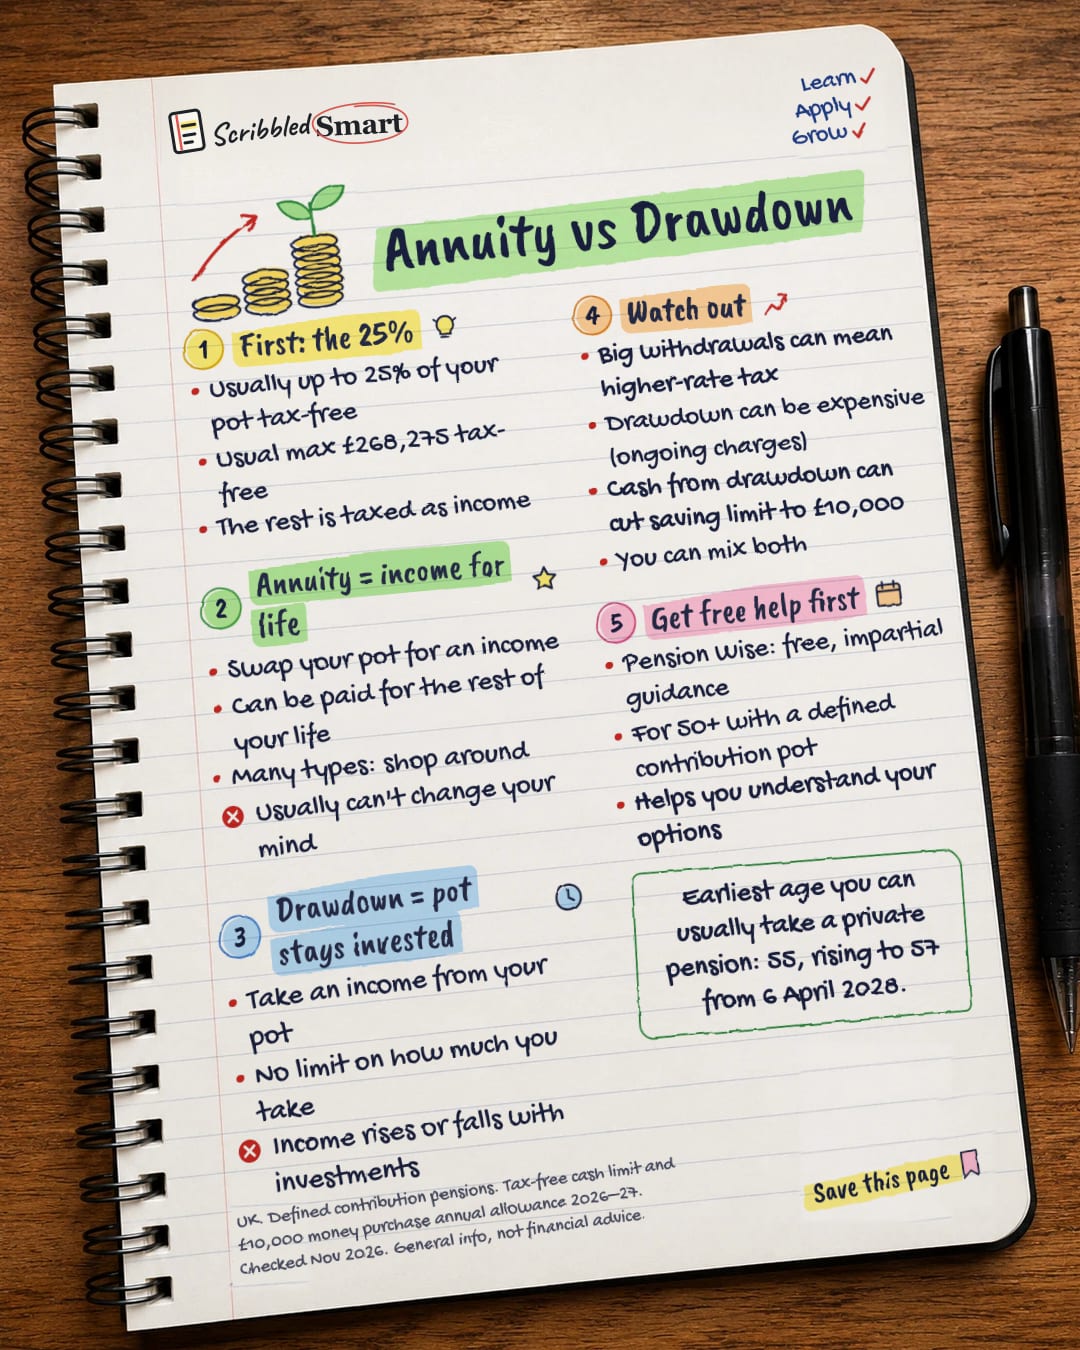
First: the 25%
- Usually up to 25% of your pot tax-free
- Usual max £268,275 tax-free
- The rest is taxed as income
Annuity = income for life
- Swap your pot for an income
- Can be paid for the rest of your life
- Many types: shop around
- Usually can't change your mind
Drawdown = pot stays invested
- Take an income from your pot
- No limit on how much you take
- Income rises or falls with investments
Watch out
- Big withdrawals can mean higher-rate tax
- Drawdown can be expensive (ongoing charges)
- Cash from drawdown can cut saving limit to £10,000
- You can mix both
Get free help first
- Pension Wise: free, impartial guidance
- For 50+ with a defined contribution pot
- Helps you understand your options
Sources
- GOV.UK: Tax when you get a pension (updated 11 Nov 2024)
- GOV.UK: Plan your retirement income
- GOV.UK: Check if you've gone above the money purchase annual allowance
- GOV.UK: Tax when you get a pension: What's tax-free (read directly 2026-11-17)
- GOV.UK: Tax on your private pension contributions: Annual allowance (read directly 2026-11-17)
- GOV.UK: Pension schemes rates (search summary 2026-11-16; read directly 2026-11-17, updated 6 April 2026)
- HMRC: Pensions Tax Manual PTM028000, Pension age
- Citizens Advice: What you can do with your pension pot (reviewed 1 Jul 2026)
- Citizens Advice: Pensions - income drawdown
- FCA: TR24/1 Retirement income advice thematic review (search summary)
- MoneyHelper: Pension Wise (search summary; site blocked)
How we checked this
Every fact on this note comes from the 11 sources listed here, checked against official or peer-reviewed sources where possible. AI tools help with drafting; a person checks every fact against the sources. How we research
Spotted a mistake? Tell us and we'll fix it and log it on the corrections page.


