
Money One-page note UK only
Is My Money Safe? FSCS Explained
What happens to your savings if your bank goes bust? Up to £120,000 is protected. Here's what counts and what doesn't. Save this page.
Good to know
UK firms. Limits checked Nov 2026. General info, not financial advice.
What's on the page
The note as text, so you can read it, copy it or use a screen reader.
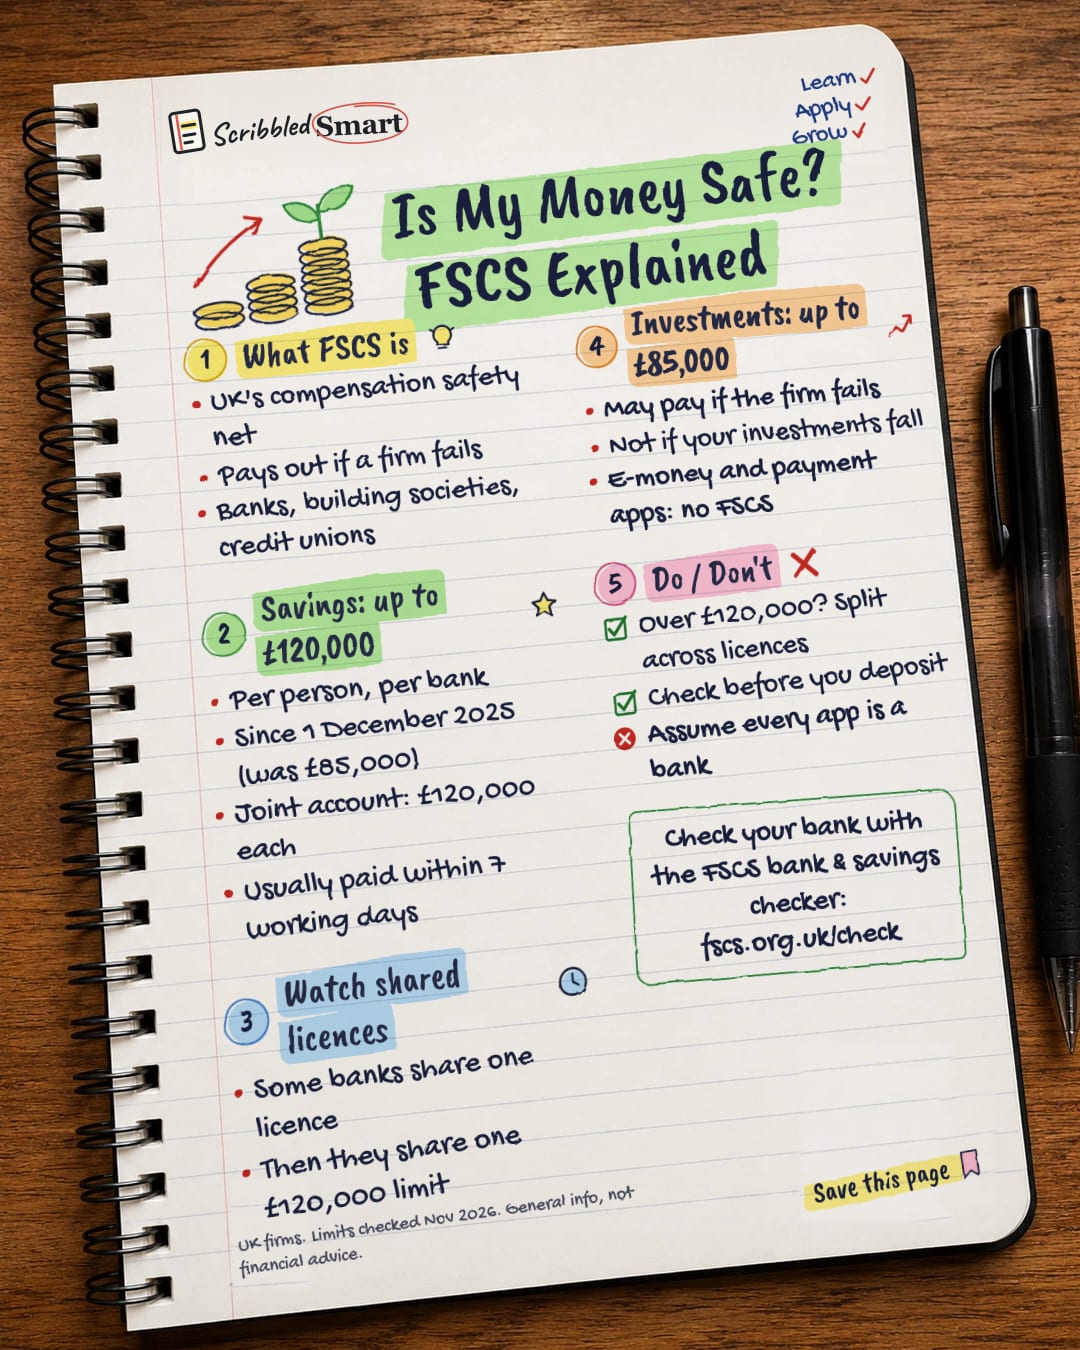
What FSCS is
- UK's compensation safety net
- Pays out if a firm fails
- Banks, building societies, credit unions
Savings: up to £120,000
- Per person, per bank
- Since 1 December 2025 (was £85,000)
- Joint account: £120,000 each
- Usually paid within 7 working days
Watch shared licences
- Some banks share one licence
- Then they share one £120,000 limit
Investments: up to £85,000
- May pay if the firm fails
- Not if your investments fall
- E-money and payment apps: no FSCS
Do / Don't
- Over £120,000? Split across licences
- Check before you deposit
- Assume every app is a bank
Sources
- FSCS: Banks, building societies and credit unions
- FSCS: Investments
- FSCS: Pots, pockets, piggy banks and vaults: e-money and FSCS protection
- FSCS: Bank & savings protection checker
- FCA: Using payment service providers
- Bank of England: List of banking and savings brands protected by the same FSCS coverage
- FSCS: Check your money's protection (landing page)
How we checked this
Every fact on this note comes from the 7 sources listed here, checked against official or peer-reviewed sources where possible. AI tools help with drafting; a person checks every fact against the sources. How we research
Spotted a mistake? Tell us and we'll fix it and log it on the corrections page.


