
Money One-page note UK only
Section 75 and Chargeback Explained
Bought something that never arrived or broke? Section 75 and chargeback may get your money back. Here's which one you get. Save this page.
Good to know
UK rules. BNPL: agreements from 15 July 2026. General info, not legal advice.
What's on the page
The note as text, so you can read it, copy it or use a screen reader.
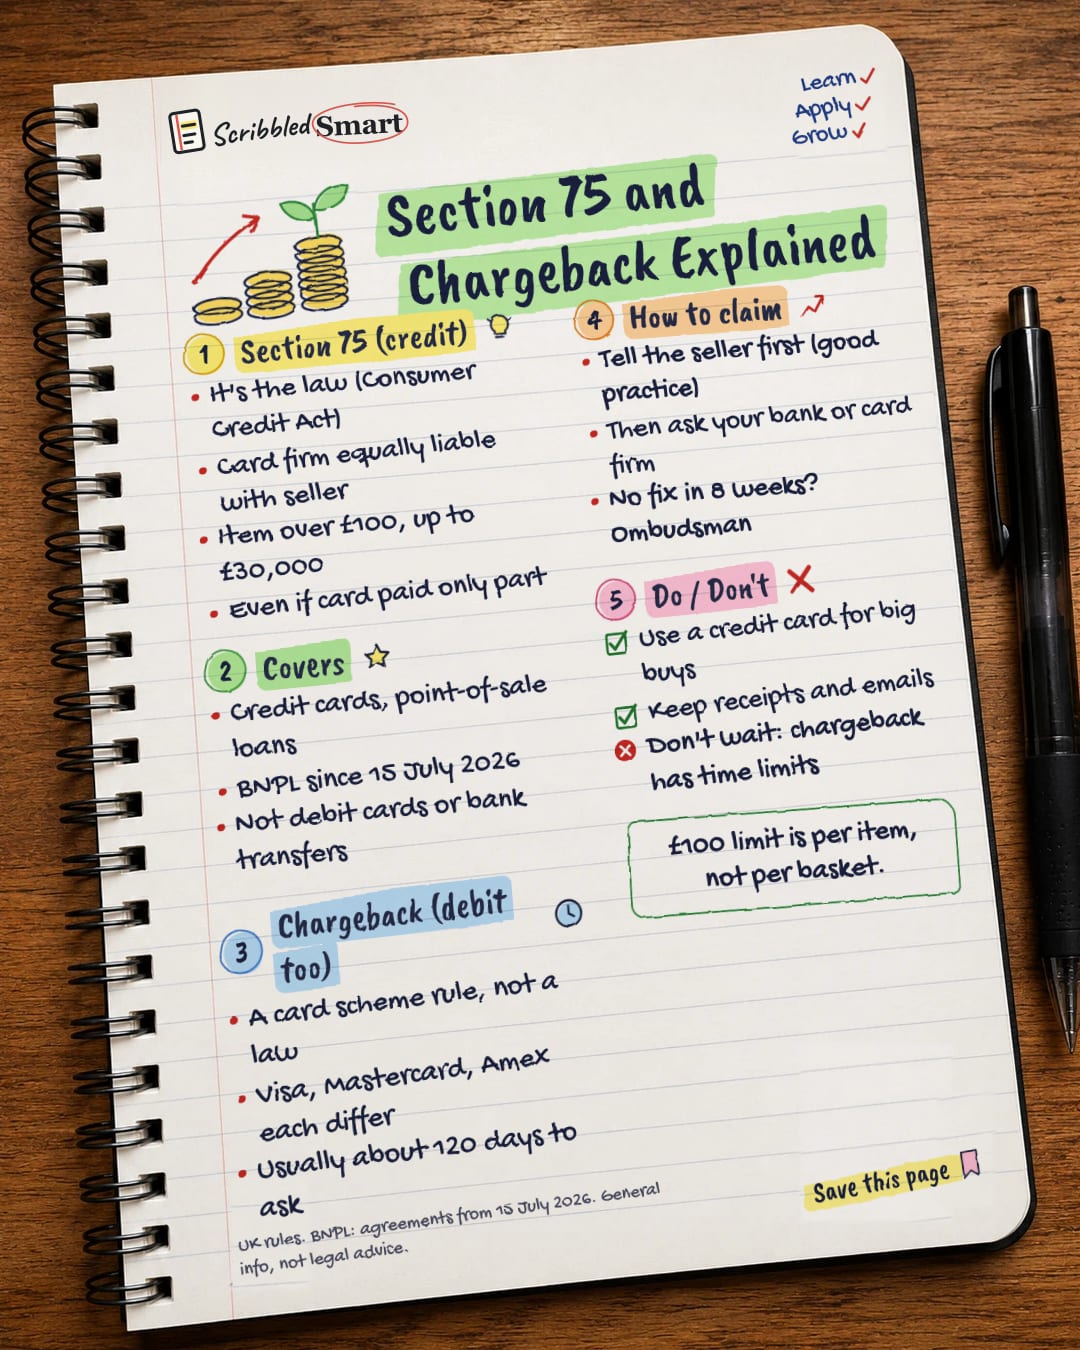
Section 75 (credit)
- It's the law (Consumer Credit Act)
- Card firm equally liable with seller
- Item over £100, up to £30,000
- Even if card paid only part
Covers
- Credit cards, point-of-sale loans
- BNPL since 15 July 2026
- Not debit cards or bank transfers
Chargeback (debit too)
- A card scheme rule, not a law
- Visa, Mastercard, Amex each differ
- Usually about 120 days to ask
How to claim
- Tell the seller first (good practice)
- Then ask your bank or card firm
- No fix in 8 weeks? Ombudsman
Do / Don't
- Use a credit card for big buys
- Keep receipts and emails
- Don't wait: chargeback has time limits
Sources
How we checked this
Every fact on this note comes from the 3 sources listed here, checked against official or peer-reviewed sources where possible. AI tools help with drafting; a person checks every fact against the sources. How we research
Spotted a mistake? Tell us and we'll fix it and log it on the corrections page.


