
On this page
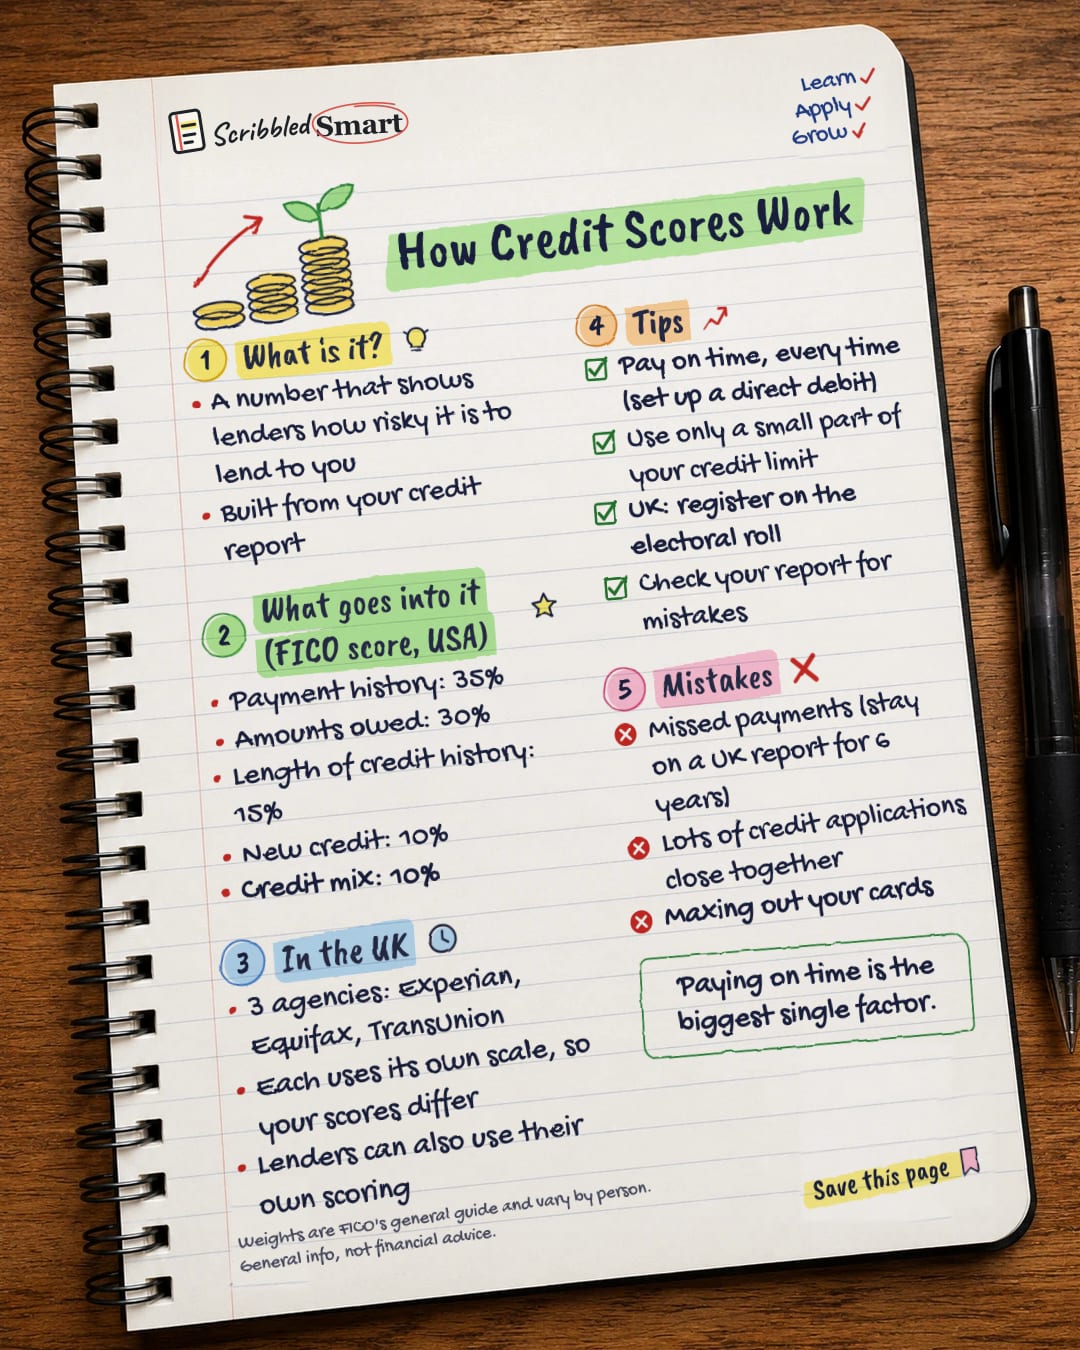
A credit score is a number that shows lenders how risky it might be to lend to you. It's built from your credit report, the record of how you've borrowed and repaid. Paying on time is the biggest single factor. Below we explain what goes into a credit score in the USA, why it works differently in the UK, and the habits that help or hurt it.
What is a credit score?
A credit score is a quick summary of your credit report. Lenders use it to judge how likely you are to pay back what you borrow. The report behind it shows your accounts, balances and payment record.
What goes into a FICO credit score in the USA?
FICO is a credit scoring model used in the USA. According to myFICO, a FICO score is built from five categories:
| Factor | Weight | What it means |
|---|---|---|
| Payment history | 35% | Whether you pay on time |
| Amounts owed | 30% | How much you owe, including how much of your credit limit you use |
| Length of credit history | 15% | How long you've had credit |
| New credit | 10% | Recent applications and new accounts |
| Credit mix | 10% | The types of credit you have |
myFICO stresses that the importance of these categories can vary from one person to another. Treat the percentages as a general guide, not a formula.
Other US models
VantageScore is another US scoring model with different weights.
How do credit scores work in the UK?
The UK works differently. There are three credit reference agencies: Experian, Equifax and TransUnion. Each one uses its own data and its own scale, according to Experian UK:
- Experian: 0–1,250
- ClearScore (uses Equifax data): 0–1,000
- Credit Karma (uses TransUnion data): 0–710
So a "good" number on one site can look very different on another. That doesn't mean something is wrong.
There's no single UK credit score
UK lenders look at your credit report and then apply their own rules. Your score on a free app is a helpful guide, but it isn't the number a lender actually uses.
How fast UK reports update
When new information comes in, UK reports usually update within about 4–6 weeks (Experian UK). So a payment you made today may not show for a while.
How to improve your credit score
These habits help in both countries, with one UK-only extra.
- ✅ Pay on time, every time. Payment history is the biggest single factor. A direct debit for at least the minimum makes it automatic.
- ✅ Use only a small part of your credit limit. "Amounts owed" includes how much of your available credit you use.
- ✅ 🇬🇧 UK only: register on the electoral roll. Experian UK and TransUnion both list it as a factor.
- ✅ Check your report for mistakes. In the UK you can get your statutory credit report free from each agency.
Explaining a missed payment (UK)
If something went wrong for a reason, such as redundancy, you can add a notice of correction to your UK credit file. It's a statement of up to 200 words explaining what happened (Experian UK).
Common credit score mistakes
- ❌ Missing payments. In the UK, missed payments stay on your report for 6 years (Experian UK, Equifax UK and StepChange agree). Their impact fades over time.
- ❌ Lots of credit applications close together. "New credit" makes up 10% of a FICO score, and Experian UK says how often you apply matters.
- ❌ Maxing out your cards. Using all your available credit pushes up the "amounts owed" factor.
If you're juggling several debts, our guide to paying off debt with the avalanche or snowball method helps you get on top of them without missing minimums.
FAQ
What affects your credit score the most?
Payment history, meaning whether you pay on time. In the FICO model it makes up about 35% of the score, the largest single part. Amounts owed come next at about 30%. myFICO notes the exact importance varies from person to person.
Why is my credit score different on different sites?
In the UK, each site uses data from a different credit reference agency, and each agency uses its own scale. Experian runs from 0 to 1,250, ClearScore (Equifax data) from 0 to 1,000, and Credit Karma (TransUnion data) from 0 to 710. Different numbers are normal.
How long do missed payments stay on your credit report in the UK?
Six years. Experian UK, Equifax UK and the debt charity StepChange all agree. The effect on your file fades over that time.
Does being on the electoral roll help your credit score?
Yes, in the UK. Experian UK lists registering on the electoral roll as a way to improve your score, and TransUnion includes the electoral register among the factors it looks at. It's one of the simplest fixes if you're not registered yet.
Can I check my credit report for free in the UK?
Yes. You can get your statutory credit report free from each of the three UK credit reference agencies: Experian, Equifax and TransUnion. It's worth checking all three, because each one uses its own data and its own scale.
Related reading
- Paying off debt: avalanche vs snowball: clear debts while keeping up every minimum payment.
- 6 money mistakes in your 20s: including borrowing without comparing.
- Compound interest explained: why unpaid card balances grow so fast.
- How to spot a scam message: protect your accounts and your credit file.
Sources
- myFICO: What's in my FICO Scores
- Experian UK: Why is my credit score different on different sites?
- Experian UK: How credit scores are calculated
- Experian UK: Late payments
- Experian UK: How to improve your credit score
- Equifax UK: Missed or late payments
- TransUnion UK: Credit score FAQ
- StepChange: DMPs and credit scores
- Experian (US): How is a FICO score calculated?
How we checked this
Every fact in this article comes from the 9 sources listed above, checked against official or peer-reviewed sources where possible. AI tools help with drafting; a person checks every fact against the sources. How we research
- Published and checked
- Next check
- yearly
Weights are FICO's general guide and vary by person. General info, not financial advice.
Spotted a mistake? Tell us and we'll fix it and log it on the corrections page.


